RV sales tax by state: rates run from 0% to 8%, and trade-ins don't cut the bill everywhere
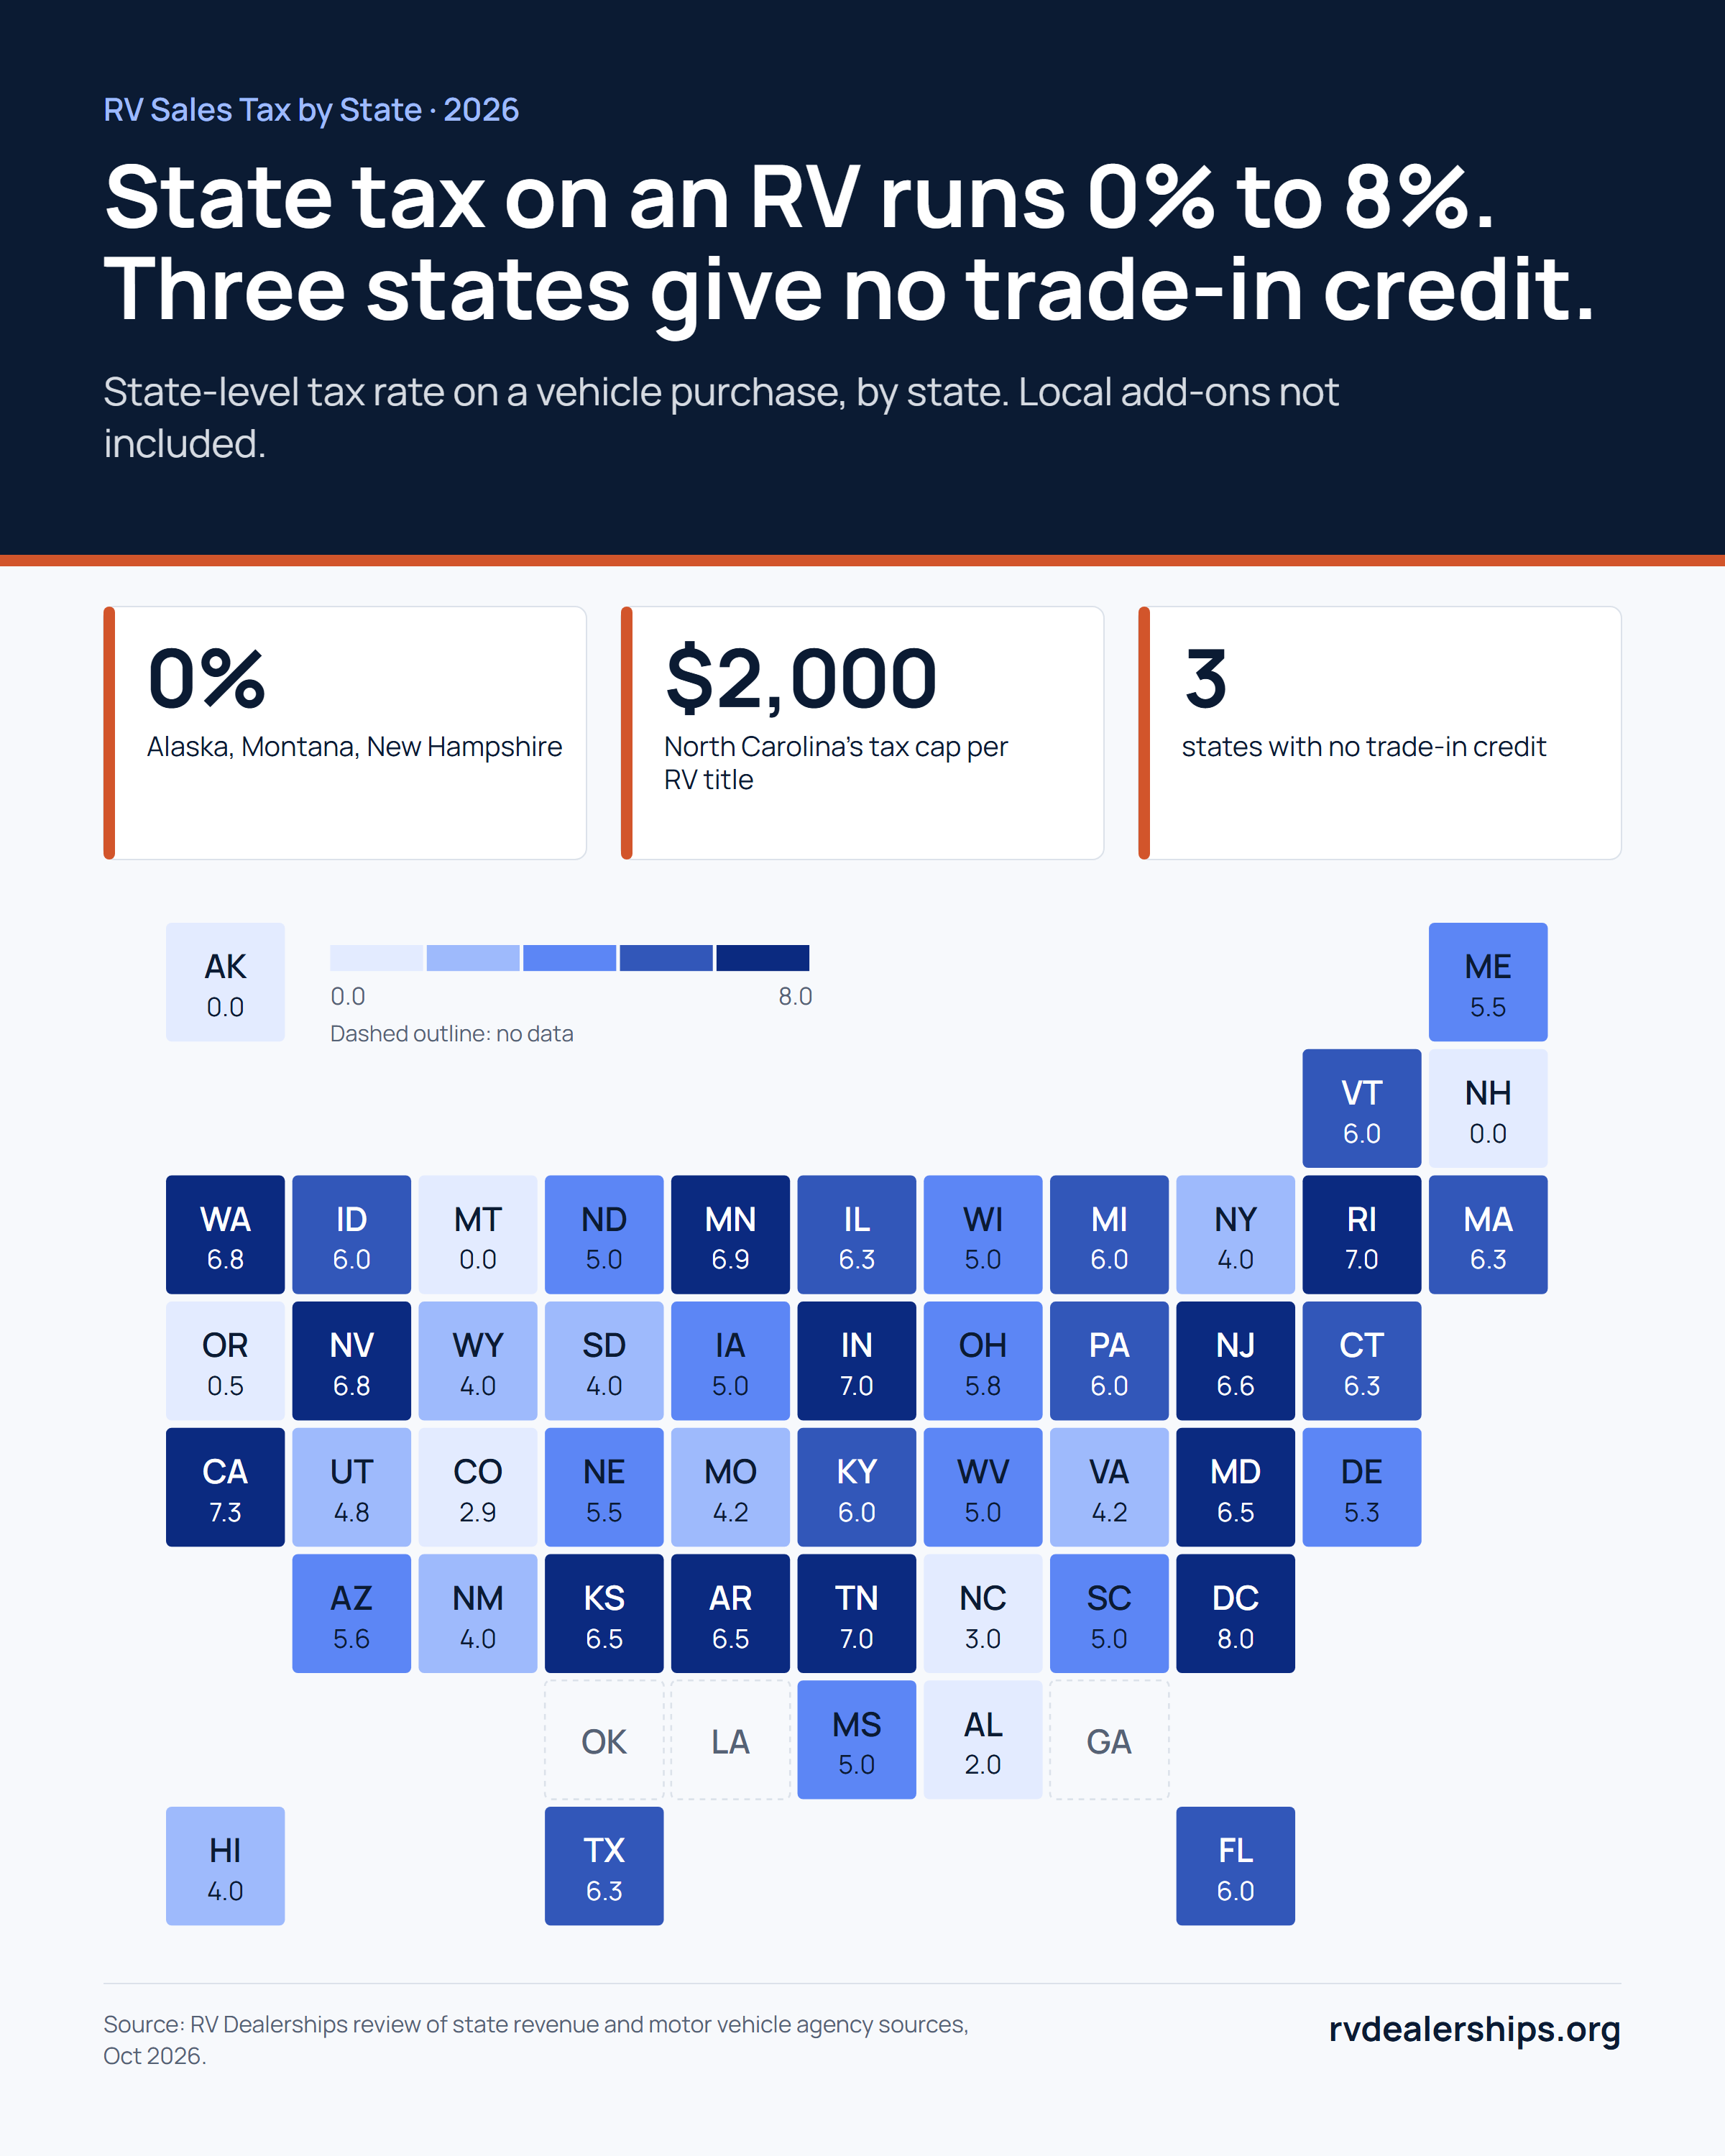
We read state revenue and motor vehicle agency pages and statutes for all 50 states and DC to log the state-level tax on a vehicle purchase, whether a trade-in lowers it, and the RV-specific quirks. Rates run from zero in Alaska, Montana and New Hampshire to an 8% titling tax on heavier vehicles in DC. California, Oregon and Virginia give no trade-in credit at all.
By the RV Dealerships research desk · Published October 25, 2026
Key findings
- Trade-ins cut the taxable price in 22 of the 32 taxing jurisdictions where we could confirm the rule, and in 7 more only partly, such as dealer sales only or new vehicles only.
- California, Oregon and Virginia give no trade-in credit. On a $60,000 motorhome with a $20,000 trade, Virginia's 4.15% applies to the full $60,000: $2,490 instead of $1,660.
- North Carolina caps its 3% highway use tax on an RV at $2,000, and South Carolina caps its 5% tax at $500. Both caps matter most on expensive motorhomes.
- Michigan caps trade-in credit on most vehicles but not on RVs, so trading one RV for another gets the full allowance.
- Indiana only credits like-kind trades. A car traded toward a travel trailer does not qualify, and nonresident RV buyers can be exempt if their home state returns the favor.
- Tax usually follows the address where you register, not the dealer's state. Buying across a state line rarely avoids tax; it often just changes who collects it.
State-level rates on the map
The map shows the state-level tax on a vehicle purchase. Many states add city, county or transit taxes on top, so the rate on your bill can be higher. Georgia, Louisiana and Oklahoma are left blank: Georgia uses a one-time title tax instead of sales tax, and we could not confirm a current rate from an official Louisiana or Oklahoma page.
Where a trade-in lowers the tax
In most states the dealer subtracts your trade-in before figuring the tax. That credit is often worth more than any haggling on price. A $30,000 trade at a 6% rate saves $1,800 in tax. Where the credit is missing or limited, selling the old rig privately and paying tax on the full price can come out about even, so run both numbers. If you plan to trade, a dealer that buys RVs can give you a written number to compare.
The full state table
Each row links to the official page or statute we read. "Not confirmed" means we could not verify that point from an official source; it does not mean the rule doesn't exist. Tax law changes, and dealers in your state handle these forms every day, so ask yours to show the math on the buyer's order.
| Alabama | 2% state automotive rate + local | Yes. Tax is on the net difference after a trade-in | Alabama dealers collect; the guide lists special rates for buyers from some other states | The 2% automotive rate also covers house trailers and truck trailers | Alabama DOR Automotive Sales, Use & Lease Tax Guide |
| Alaska | No statewide sales tax (local taxes may apply) | No state tax to reduce | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates |
| Arizona | 5.6% state TPT + city tax | Not confirmed | Nonresidents from states with a lower rate and tax reciprocity can be exempt from the state portion; city tax still applies | None found | Arizona DOR: Motor Vehicle Sales |
| Arkansas | 6.5% state + local | Yes. Trade-in credit, and the same credit if you sell your old vehicle privately within 60 days | Not confirmed | Travel trailers are not motor vehicles for the local tax cap, so local tax applies to the full invoice | Arkansas DFA: credit for sale of a used vehicle; Arkansas DFA sales and use tax FAQs |
| California | 7.25% statewide base (includes 1.25% local) + district taxes | No. CDTFA says the value of a trade-in is taxable | Not confirmed | None found | CDTFA Publication 73 |
| Colorado | 2.9% state + local | Not confirmed | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates (Colorado sources could not be read) |
| Connecticut | 6.35%; 7.75% for vehicles over $50,000 | Yes. Full trade-in credit on dealer purchases | Paid at registration; if you paid less than Connecticut's rate in another state, you pay the difference | None found | CT DMV: sales tax and registrations |
| Delaware | No sales tax; 5.25% document fee ($5.25 per $100) at titling | Yes. Fee is on price less trade-in; a private sale of your old vehicle within 60 days also earns credit | Paid to the DMV when you title in Delaware | The fee applies to trailers as well as motor vehicles | 30 Del. C. ch. 30 (motor vehicle document fee) |
| District of Columbia | 6% to 8% titling excise by vehicle weight | Not confirmed | Paid to DC DMV at titling | Vehicles of 5,000 lb or more fall in the 8% class in the code | D.C. Code § 50-2201.03 |
| Florida | 6% state + county surtax | Yes. Used articles taken in trade are deducted | Not confirmed | None found | Fla. Stat. 212.09 (trade-ins deducted) |
| Georgia | One-time title ad valorem tax (TAVT) on fair market value instead of sales tax | Dealer sales only. No trade-in reduction on private sales | Paid at titling in Georgia | Not confirmed | Georgia DOR TAVT FAQ |
| Hawaii | 4% general excise tax + county surcharge | Not confirmed | Not confirmed | None found | Hawaii DOT: General Excise Tax |
| Idaho | 6% | Yes. Trade-in allowances reduce the taxable price | Use tax is due if you paid less than 6% in another state | None found | Idaho State Tax Commission sales and use tax guide |
| Illinois | 6.25% state + local | Dealer sales only. No trade-in allowance on private sales (Form RUT-50) | Use tax due when you bring the vehicle into Illinois; credit for tax properly paid elsewhere | None found | Illinois DOR Form RUT-25 instructions; Illinois DOR Form RUT-50 instructions |
| Indiana | 7% | Like-kind only: a motor vehicle for a motor vehicle, or a trailer for a trailer | Buyers registering in another state within 30 days may pay their home state's rate | Nonresident RV and cargo trailer buyers are exempt if their home state gives Indiana residents the same treatment (Form ST-137RV) | Indiana DOR Sales Tax Information Bulletin 28S |
| Iowa | 5% fee for new registration (plus $10) | Yes, when the same owner is on both titles | Paid to the county treasurer at registration | None found | Iowa Code § 321.105A |
| Kansas | 6.5% state + local | Dealer sales only. No trade-in allowance between individuals | Not confirmed | None found | Kansas DOR Pub. KS-1526 |
| Kentucky | 6% motor vehicle usage tax | Trade-in allowance on new vehicles since July 1, 2014; used vehicles use a value formula | Collected by the county clerk at registration; credit for tax paid to a state that returns the favor | None found | Kentucky DOR: Motor Vehicle Usage Tax |
| Louisiana | Not confirmed | Not confirmed | Not confirmed | Not confirmed | No Louisiana source we could read stated the vehicle rate |
| Maine | 5.5% sales tax + municipal excise tax | Not confirmed | Sales tax paid at registration; excise tax paid at the town office | Motor homes pay the 5.5% sales tax plus the municipal excise tax | Maine BMV: register a motor home |
| Maryland | 6.5% vehicle excise tax | Yes. Dealer form deducts the trade-in allowance | New residents pay the difference if their previous state's rate was below 6.5% | None found | Maryland MVA: excise tax; MVA dealer form |
| Massachusetts | 6.25% | Not confirmed | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates (Massachusetts sources could not be read) |
| Michigan | 6% (no local sales tax) | Capped Michigan trade-in allowance for most vehicles | Not confirmed | Trade-ins of RVs are not subject to the cap | Michigan Treasury Form 5081 instructions; Michigan Treasury: sales and use tax |
| Minnesota | 6.875% motor vehicle sales tax | Yes. Trade-in value is deducted from the selling price | Applies to vehicles bought in or outside Minnesota that must be registered there | None found | Minn. Stat. § 297B.01; Minn. Stat. § 297B.02 |
| Mississippi | 5% vehicle rate | Yes. Tax is on the net price after trade-ins | Sales tax paid to another state is not credited | None found | Mississippi DOR motor vehicle FAQ |
| Missouri | 4.225% state + local | Yes. Tax is on the price less trade-in allowance | Paid when you title in Missouri; if you paid less elsewhere, you pay the difference | None found | Missouri DOR: titling and registration |
| Montana | No general sales tax | No state tax to reduce | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates |
| Nebraska | 5.5% state + local | Yes. Form 6 deducts the trade-in allowance | Credit for tax properly paid to another state | None found | Nebraska DOR Form 6; Nebraska DOR: sales and use tax |
| Nevada | 6.85% state + local | Yes. A dealer's allowance for a used vehicle taken in trade is excluded | Not confirmed | None found | NRS 372.025 (chapter 372); rate: Indiana DOR table of other states' vehicle tax rates |
| New Hampshire | No general sales tax | No state tax to reduce | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates |
| New Jersey | 6.625% | Not confirmed | Not confirmed | New vehicles may owe an extra 0.4% luxury and fuel-inefficient surcharge | NJ MVC: titling a new vehicle; rate: Indiana DOR table of other states' vehicle tax rates |
| New Mexico | 4% motor vehicle excise tax | Yes. Tax is on the price less trade-in credit | Paid at titling; tax paid to another state can be credited | None found | New Mexico TRD: Motor Vehicle Excise Tax |
| New York | 4% state + local | Yes, when the dealer takes the trade-in for resale | Not confirmed | None found | NY Tax Bulletin ST-860 |
| North Carolina | 3% highway use tax | Yes. Retail value is the sales price less the trade-in allowance | Paid when the title is issued | The tax on an RV is capped at $2,000 per title | N.C. Gen. Stat. § 105-187.3 |
| North Dakota | 5% motor vehicle excise tax | Yes. Trade-in value is deducted | Applies to vehicles bought in or outside North Dakota | Travel trailers are included in the excise tax | N.D. Cent. Code ch. 57-40.3 |
| Ohio | 5.75% state + county | New vehicles only. A trade-in does not reduce tax on a used vehicle | Paid at the clerk of courts title office | None found | Ohio Dept. of Taxation: motor vehicles; Ohio Dept. of Taxation: sales and use tax |
| Oklahoma | 1.25% sales tax plus a motor vehicle excise tax | Not confirmed | Not confirmed | Not confirmed | Indiana DOR table of other states' vehicle tax rates (Oklahoma excise rate not confirmed) |
| Oregon | No sales tax; 0.5% vehicle privilege tax (dealer sales) or use tax (bought out of state) | No. Trade-ins do not reduce the taxable price | Use tax applies to vehicles bought from out-of-state dealers and registered in Oregon | Applies to travel trailers and fifth wheels that meet the criteria | Oregon DOR: vehicle privilege and use taxes |
| Pennsylvania | 6% (+1% Allegheny County, +2% Philadelphia) | Not confirmed | Not confirmed | None found | Pennsylvania DOR: sales, use and hotel occupancy tax |
| Rhode Island | 7% | Not confirmed | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates (Rhode Island sources could not be read) |
| South Carolina | 5%, capped at $500 (Infrastructure Maintenance Fee) | Not confirmed | The fee is paid to SCDMV for vehicles that must be registered | RVs, travel trailers, fifth wheels and motor homes are on the capped list | SCDOR: Maximum Tax |
| South Dakota | 4% motor vehicle excise tax | Not confirmed | New residents owe no more tax if their previous state's rate was higher | Motorhomes and RVs are titled under the same system | South Dakota DOR: motor vehicle |
| Tennessee | 7% state + local | Yes. Credit for used items taken in trade | Not confirmed | None found | Tennessee DOR auto dealership tax guide |
| Texas | 6.25% motor vehicle sales tax | Yes. Tax is on the price minus the trade-in allowance | Texas residents owe use tax on out-of-state purchases, less tax paid elsewhere; new residents pay $90 | None found | Texas Comptroller: motor vehicle sales and use tax |
| Utah | 4.85% state + local | Yes. Taxable price is after trade-in credit | Dealer sales use the dealer location's rate; Utah residents buying out of state get credit for tax paid there | None found | Utah State Tax Commission Pub. 5; rate: Indiana DOR table of other states' vehicle tax rates |
| Vermont | 6% purchase and use tax | Not confirmed | Due at registration or titling | Motor homes are taxed at 6% | Vermont DMV: vehicle taxation; 32 V.S.A. § 8903 |
| Virginia | 4.15% motor vehicle sales and use tax | No. Trade-in credit is not deducted | First-time Virginia titling is exempt if already titled in your name elsewhere (proof of tax if bought within 12 months) | None found | Virginia DMV: motor vehicle sales and use tax |
| Washington | 6.5% state + 0.3% motor vehicle tax + local | Yes, for trade-in property of like kind | Sales to qualified nonresidents can be exempt | None found | RCW 82.08.010 and 82.08.020; Washington DOR: sales tax exemption for nonresidents |
| West Virginia | 5% privilege tax at titling | Not confirmed | Paid to the DMV before a title is issued | RVs and house trailers are subject to the privilege tax | W. Va. Code § 17A-3-4 |
| Wisconsin | 5% state + county | Yes, when the sale and trade-in are one transaction | Credit for tax paid to another state | None found | Wisconsin DOR Publication 202 |
| Wyoming | 4% state + local | Not confirmed | Not confirmed | None found | Indiana DOR table of other states' vehicle tax rates (Wyoming sources could not be read) |
State-level rates only; local taxes may apply. Read October 25, 2026. Not legal or tax advice. Download this table (CSV)
Buying an RV in another state
The general pattern is simple: you owe tax to the state where the RV will be registered. A dealer in another state may collect your home state's tax and send it in, or collect nothing and leave you to pay when you title at home. If you pay the selling state's tax by mistake, most home states credit it, but some do not. Mississippi says tax paid to another state is not credited, and Kentucky only credits states that return the favor.
- Ask the dealer which state's tax they are collecting and get it written on the buyer's order.
- Keep the receipt for any tax you paid elsewhere. Connecticut, Missouri, Nebraska, New Mexico, Texas, Utah and Wisconsin all describe a credit for tax paid to another state.
- Check for nonresident exemptions. Arizona, Indiana and Washington exempt some out-of-state buyers. Indiana's RV exemption depends on whether your home state treats Indiana buyers the same way.
- Moving states with an RV you already own? Several states, including Texas ($90 new-resident tax), Virginia and South Dakota, charge little or nothing if the rig was already titled in your name.
What it means for you
- Price the tax before you negotiate. Multiply the state rate (plus local) by the price after any trade-in your state allows.
- Decide trade versus private sale with the tax in mind. In a full-credit state the tax savings belong in your trade-in math.
- Watch the caps. On a $150,000 motorhome, North Carolina's $2,000 cap and South Carolina's $500 cap change the total a lot.
- Compare the whole bill, not just the rate. Doc fees vary as much as tax. See our doc fee rules by state.
- If you buy at a show, plan for where the paperwork gets signed. Our 2027 RV show calendar lists the big shows, and our Sunday sales map shows where dealers can close on a Sunday.
The infographic
Free to use with a link. Publish the graphic or the numbers anywhere, as long as you credit RV Dealerships with a link to this page.
How we did this
- Between October 24 and 25, 2026 we read state revenue department and motor vehicle agency pages, tax forms, dealer guides and statutes for all 50 states and DC. Each row cites the page we relied on.
- The rate column is the state-level tax on a vehicle purchase. Local taxes are noted where the source mentions them but are not included in the map.
- For Alaska, Colorado, Massachusetts, Montana, New Hampshire, Oklahoma, Rhode Island and Wyoming, and for the Nevada, New Jersey and Utah rates, we could not read a usable page from that state, so the rate comes from the Indiana Department of Revenue's published table of other states' vehicle tax rates (last reviewed September 25, 2024). Those rows say so.
- We marked a trade-in as "Partly" when the credit applies only to dealer sales, only to new vehicles, only to like-kind trades, or is capped. Where we could not verify a point, the cell says "Not confirmed" and the state is left blank on that map.
- Rates change. Maryland raised its excise tax to 6.5% and Louisiana changed its state rate in 2025, which is why we did not rely on older summaries for those states.
Not legal advice. Laws and agency rules change. Each row links the source we read and the date we checked it; confirm with the agency or an attorney before you rely on it.
Sources
- Alabama DOR Automotive Sales, Use & Lease Tax Guide, accessed October 25, 2026
- Arizona DOR: Motor Vehicle Sales, accessed October 25, 2026
- Arkansas DFA: credit for sale of a used vehicle, accessed October 25, 2026
- Arkansas DFA sales and use tax FAQs, accessed October 25, 2026
- CDTFA Publication 73, accessed October 25, 2026
- CT DMV: sales tax and registrations, accessed October 25, 2026
- 30 Del. C. ch. 30 (motor vehicle document fee), accessed October 25, 2026
- D.C. Code § 50-2201.03, accessed October 25, 2026
- Fla. Stat. 212.09 (trade-ins deducted), accessed October 25, 2026
- Georgia DOR TAVT FAQ, accessed October 25, 2026
- Hawaii DOT: General Excise Tax, accessed October 25, 2026
- Idaho State Tax Commission sales and use tax guide, accessed October 25, 2026
- Illinois DOR Form RUT-25 instructions, accessed October 25, 2026
- Illinois DOR Form RUT-50 instructions, accessed October 25, 2026
- Indiana DOR Sales Tax Information Bulletin 28S, accessed October 25, 2026
- Iowa Code § 321.105A, accessed October 25, 2026
- Kansas DOR Pub. KS-1526, accessed October 25, 2026
- Kentucky DOR: Motor Vehicle Usage Tax, accessed October 25, 2026
- Maine BMV: register a motor home, accessed October 25, 2026
- Maryland MVA: excise tax, accessed October 25, 2026
- Michigan Treasury Form 5081 instructions, accessed October 25, 2026
- Michigan Treasury: sales and use tax, accessed October 25, 2026
- Minn. Stat. § 297B.01, accessed October 25, 2026
- Minn. Stat. § 297B.02, accessed October 25, 2026
- Mississippi DOR motor vehicle FAQ, accessed October 25, 2026
- Missouri DOR: titling and registration, accessed October 25, 2026
- Nebraska DOR Form 6, accessed October 25, 2026
- Nebraska DOR: sales and use tax, accessed October 25, 2026
- NRS 372.025 (chapter 372), accessed October 25, 2026
- NJ MVC: titling a new vehicle, accessed October 25, 2026
- New Mexico TRD: Motor Vehicle Excise Tax, accessed October 25, 2026
- NY Tax Bulletin ST-860, accessed October 25, 2026
- N.C. Gen. Stat. § 105-187.3, accessed October 25, 2026
- N.D. Cent. Code ch. 57-40.3, accessed October 25, 2026
- Ohio Dept. of Taxation: motor vehicles, accessed October 25, 2026
- Ohio Dept. of Taxation: sales and use tax, accessed October 25, 2026
- Oregon DOR: vehicle privilege and use taxes, accessed October 25, 2026
- Pennsylvania DOR: sales, use and hotel occupancy tax, accessed October 25, 2026
- SCDOR: Maximum Tax, accessed October 25, 2026
- South Dakota DOR: motor vehicle, accessed October 25, 2026
- Tennessee DOR auto dealership tax guide, accessed October 25, 2026
- Texas Comptroller: motor vehicle sales and use tax, accessed October 25, 2026
- Utah State Tax Commission Pub. 5, accessed October 25, 2026
- Vermont DMV: vehicle taxation, accessed October 25, 2026
- 32 V.S.A. § 8903, accessed October 25, 2026
- Virginia DMV: motor vehicle sales and use tax, accessed October 25, 2026
- RCW 82.08.010 and 82.08.020, accessed October 25, 2026
- Washington DOR: sales tax exemption for nonresidents, accessed October 25, 2026
- W. Va. Code § 17A-3-4, accessed October 25, 2026
- Wisconsin DOR Publication 202, accessed October 25, 2026
- Indiana DOR table of other states' vehicle tax rates, accessed October 25, 2026. Used only where a state's own page could not be read; table last reviewed by Indiana DOR on Sept 25, 2024.
Cite this: RV Dealerships, "RV sales tax by state: rates run from 0% to 8%, and trade-ins don't cut the bill everywhere," October 25, 2026, https://rvdealerships.org/rv-sales-tax-by-state/
Spotted an error or have newer data? Tell us and we'll check it and update the page.
Questions people ask
Do you pay sales tax where you buy an RV or where you register it?
Usually where you register it. Most states charge their own sales or use tax when you title the RV, and many credit tax you already paid to another state. Some dealers collect your home state's tax for you. Mississippi does not credit tax paid elsewhere, so ask before you pay twice.
Which states have no sales tax on RVs?
Alaska, Montana and New Hampshire have no general state sales tax, though Alaska allows local taxes. Delaware has no sales tax but charges a 5.25% document fee when you title, and Oregon charges a 0.5% vehicle privilege or use tax, including on travel trailers and fifth wheels.
Does a trade-in reduce sales tax on an RV?
In most states, yes: we confirmed full trade-in credit in 22 jurisdictions. California, Oregon and Virginia give none. Others limit it: Ohio credits trade-ins only on new vehicles, Illinois and Kansas only on dealer sales, and Indiana only on like-kind trades.
Is there a cap on sales tax for RVs?
In some states. North Carolina caps its 3% highway use tax at $2,000 per title for recreational vehicles. South Carolina taxes RVs, travel trailers, fifth wheels and motor homes at 5% up to $500. Most other states have no cap.
Can I avoid RV sales tax by buying in a state with no sales tax?
Generally no. Your home state charges its tax when you register the RV there. Buying in Oregon or Montana as a resident of another state usually means paying your home state's tax at titling instead of at the dealer.